

Marketing automation for lenders
Borrowers want plain answers before they apply, and brokers want to know what you'll lend on this month. Maggie, your AI CMO, writes guides, product explainers and broker updates for your website and LinkedIn, and nothing goes out until your team approves it.
Free to start · No credit card · 30 free posts
Used by 600+ users and trusted by teams at
aeglesriphal.com
moonlakespa.com
shop.theteagroup.com
clo100.com
logtrics.io
mymorez.com
nextidal.com
otisapp.com
storaitelling.com
theheatpumps.co.uk
web-translations.com
exposeai.tech
orielipo.com
whitelabelcrowd.fund
elliptic.co
med.moonlakespa.com
netdex.co.il
orawellness.uk
reenest.com
syngage.ai
thepenthouseliving.com
zengolf.studio
imaintain.uk
rebuildingsociety.com
aurasocial.world
goaimex.com
moneyparents.com
newgenrenewables.uk
osmosisai.co
saunders.ac
teeza.app
thursdayclub.com
Why lenders struggle to keep their marketing going
Every word about a loan has to be right, so marketing moves slowly, and the people who could write it are busy underwriting.
Every post needs a compliance check
Financial promotions have to be clear, fair and not misleading, so a simple LinkedIn post can wait days for sign-off. Most weeks, nothing goes out at all.
Brokers forget who lends on what
Intermediaries place cases with the lenders they think of first. When your criteria change or you launch a product, a single email is easy to miss in a busy broker's inbox.
Borrowers can't find straight answers
People searching for how bridging works, what a lender looks for or how long a business loan takes find comparison sites and forums. Your own clear explanations are missing from those results.
Rate changes outpace your website
When base rate moves or the market shifts, borrowers and brokers look for what it means for them. If your website still talks about last year's market, they look somewhere else.
Your criteria changed on Monday, and brokers are reading about it by Thursday.
It's Monday. Your credit committee has just widened the property types you'll lend on, and your BDMs have been asking for something to share with brokers. The website still has a news post from the spring.
You paste your website into cmo.so. Maggie reads it and writes your brand profile: your bridging and buy-to-let products, the brokers and professional landlords you work with, your fast, case-by-case underwriting, your competitors and your plain, confident voice. You correct one thing: you only lend through brokers, never direct to borrowers. You turn on Content Policy Guard with financial rules and add your own: never promise approval or a completion date.
By Tuesday the drafts are waiting, each with a picture in your look: a LinkedIn post for brokers on the new property types, a blog guide explaining how bridging finance works from application to exit, a post on what lenders look for in a refurbishment project, and a Google Business update for people searching for you by name. Content Policy Guard held one sentence that read like a promise of speed, with a suggested rewrite. Your compliance lead reads each post, approves three and edits the fourth.
The posts go out at the times you set for each channel and each comes back with its link. While your team works on cases, Maggie is already planning a guide on what a rate change means for landlords, and Search Console in cmo.so shows which guides brokers and borrowers are finding.
A marketing assistant built for careful lenders
Each of those problems has an answer, and your team still decides what goes out under your name.
Borrower guides on your blog
Plain-English guides on how your products work, what the application involves and what borrowers should prepare, written for Google and for AI answers. Published to your WordPress, Wix, Webflow or Shopify site, or any site through the cmo.so API.
Blog on autopilotBroker updates on LinkedIn
Posts on criteria changes, new products and the cases you like to see, written for brokers and introducers and queued so your BDMs always have something current to share.
LinkedInA check before anything goes out
Turn on Content Policy Guard and posts are checked against financial rules, or your own house rules. A risky post is held as a draft with a suggested rewrite. These are AI suggestions, not legal or compliance advice, and a qualified person should still review every post.
Content Policy GuardYour products, not generic finance copy
Enter your website and Maggie builds your brand profile: your products, the borrowers and brokers you serve, what sets your lending apart, competitors and voice. Every post and picture starts from it.
Brand profileSeen in search and AI answers
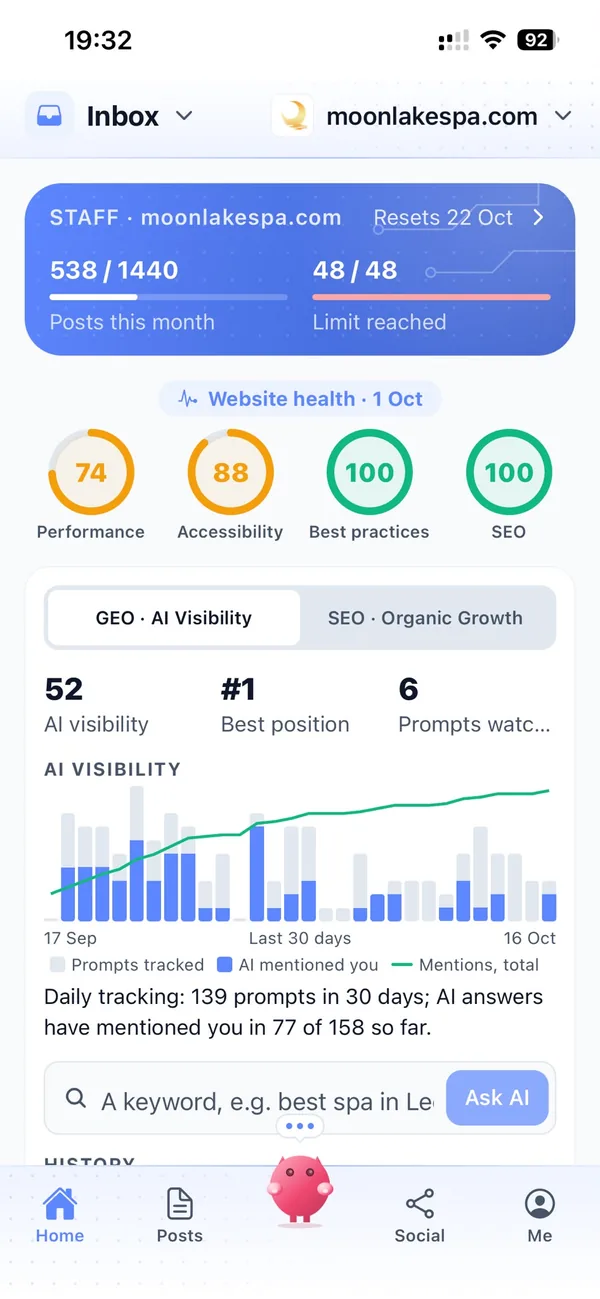
Search Console shows which guides bring people to your website, and AI visibility shows how Google's AI answers describe your business when someone asks about your kind of lending.
AI visibility and Search ConsoleApprovals that fit your sign-off
By default nothing goes out until it is approved. Add your compliance lead in Me → Team, keep approvals on for every channel, and every published post is reported back with its link for your records.
ApprovalsYour marketing team, in your pocket
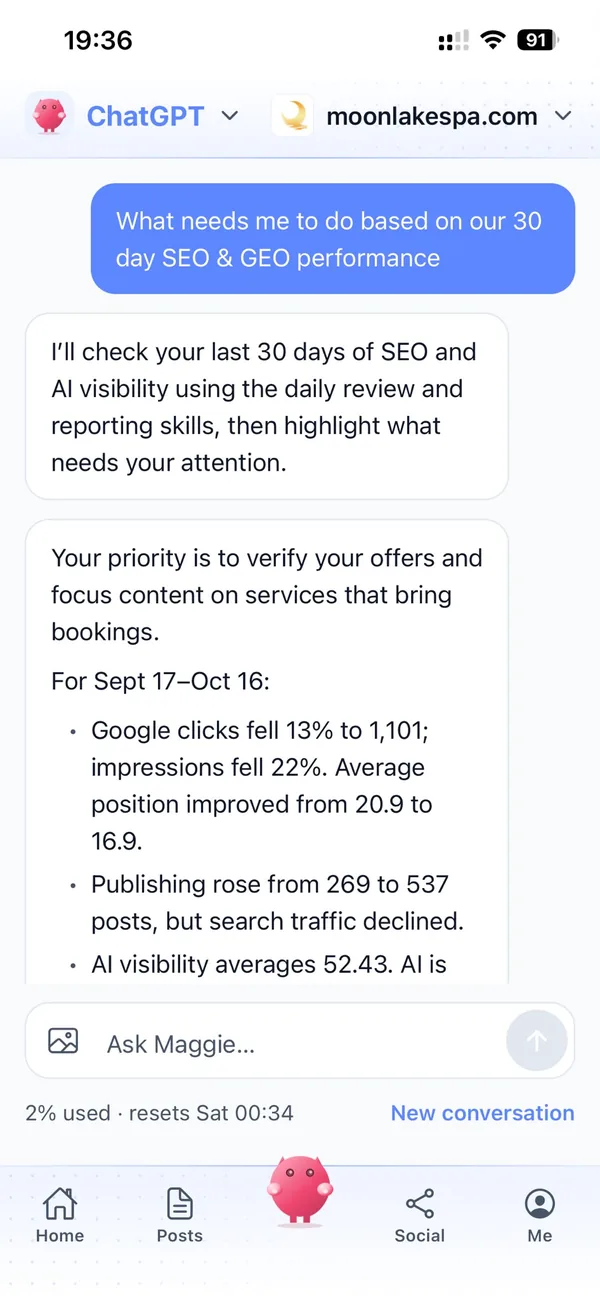
Real screens from the cmo.so app on iPhone.
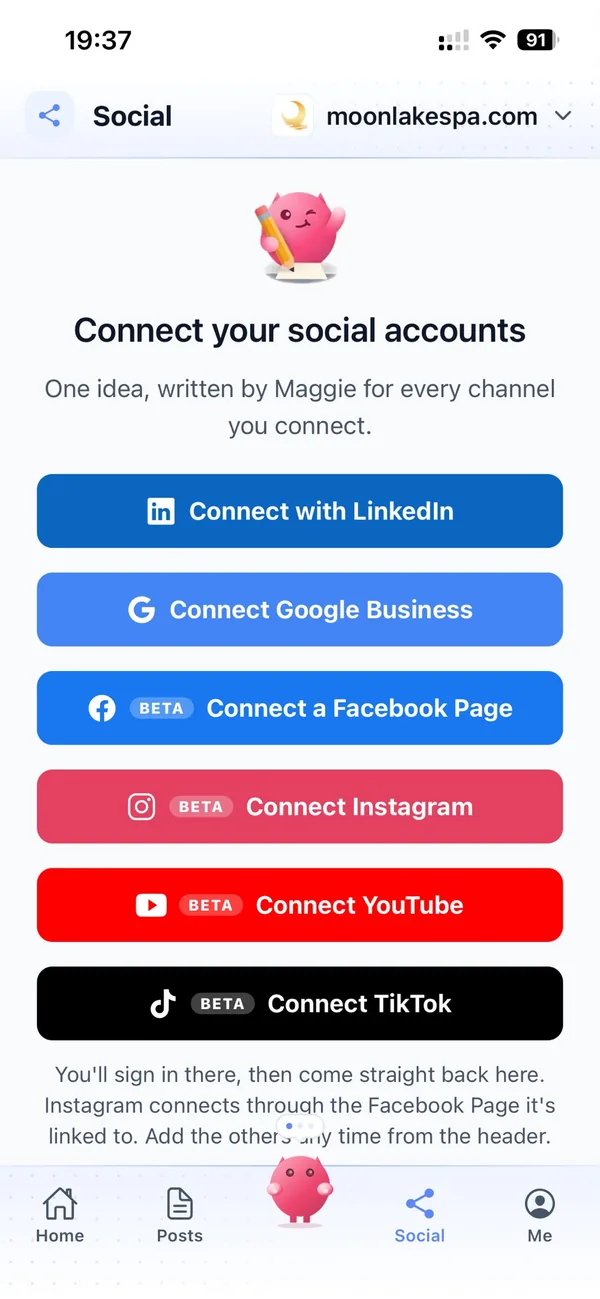
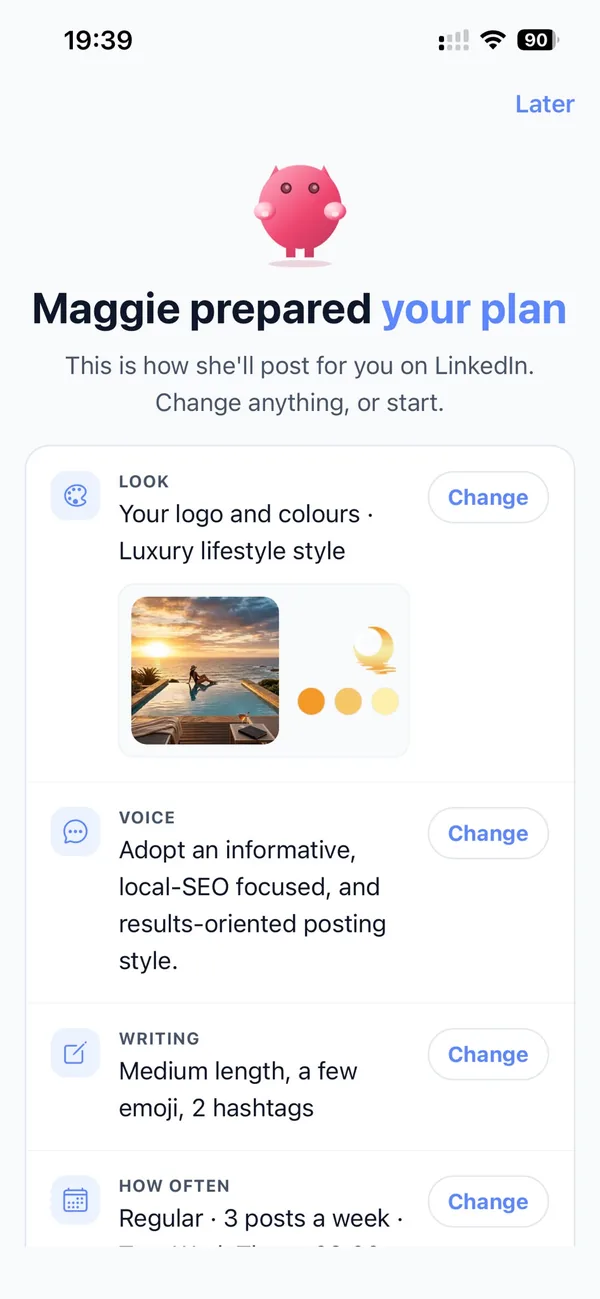
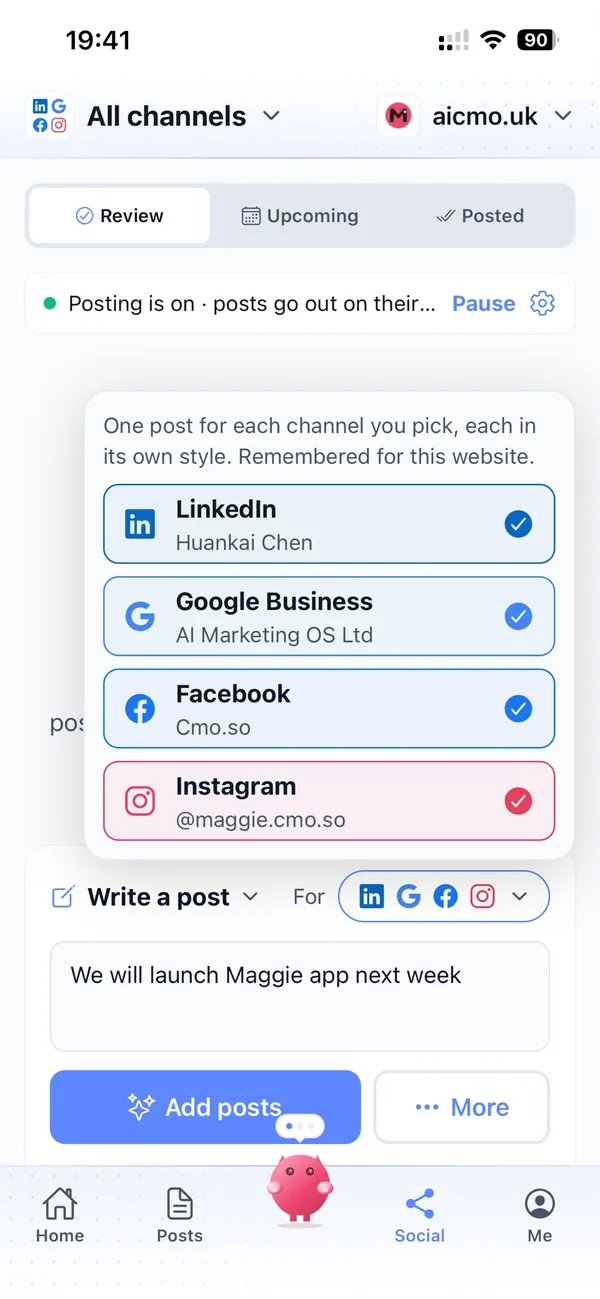
From your website to approved, steady content in four steps
Enter your website
Maggie reads it and drafts your brand profile in minutes.
Check your profile
Correct your products and who you lend to, turn on Content Policy Guard, add your house rules and choose your channels.
Review the drafts
Your first week of posts arrives with pictures. Your team approves, edits or skips each one.
Let them go out
Approved posts go out at each channel's times and every one comes back with its link.
Why not just…
The usual ways lenders try to stay visible, and where each one runs out.
…rely on BDMs and broker emails?
Your BDMs build the relationships, but they can't be in every broker's feed every week. Regular LinkedIn posts and guides keep your name in front of brokers between calls.
…leave it to comparison and sourcing platforms?
They list your products alongside everyone else's, with no room to explain your approach. Guides on your own website show brokers and borrowers why they should choose you.
…hire a financial services marketing agency?
SEO and content agencies often cost around £1,000 a month, and specialist financial agencies can cost more. Maggie writes and publishes every week from £15 a month, with your team approving each post.
…write it with ChatGPT?
You still brief it, check it, make the picture and post it yourself, and it doesn't know your criteria or your rules. Maggie remembers your business, checks posts with Content Policy Guard if you turn it on, and puts them out on schedule.
Cut the £5,900/mo marketing bill to £15/mo
Everything a marketing team does, done by Maggie.
| What needs doing | Without cmo.so | With cmo.so |
|---|---|---|
| Full-time marketing hire | £3,000/mo | Included |
| SEO and AI search (GEO) agency | £1,000/mo | Included |
| Content writer, AI-assisted | £500/mo | Included |
| Social media manager, freelance | £800/mo | Included |
| Designed pictures for every post | £300/mo | Included |
| SEO and GEO softwareRank tracking, site audits, AI visibility | £250/mo | Included |
| AI writing and image tools | £50/mo | Included |
| Working hours | Office hours | 24/7 |
| Total per month | £5,900+ | From £15/mo |
Typical UK costs for a small business in 2026, with AI already cutting freelance rates. Estimates only; your own quotes will vary.
- 5 social posts, 30 once verified
- 15 Maggie messages a day
- Upgrade any time
- 12 posts a day
- 150 Maggie messages a day
- All channels
- 96 posts a day
- 1,000 Maggie messages a day
- All channels
Per website, billed monthly. Blog and social posts share one allowance; your best plan sets how much you can talk to Maggie across all your websites.
Marketing automation for lenders: your questions
Still unsure?
What is marketing automation for lenders?
It's software that does the repeating work of marketing a lending business: planning topics, writing guides, broker updates and social posts, making pictures and publishing them on schedule.
With cmo.so, Maggie does all of it from your website, and nothing goes out until your team approves it.
How do lenders get more customers online?
Lenders get more customers online by explaining their products clearly where borrowers and brokers look: helpful guides on their own website, regular LinkedIn posts for intermediaries and an up-to-date Google Business profile.
Maggie writes those posts every week, and Search Console shows which ones bring people to your website.
Is it safe to use AI for financial marketing?
It is safe when a qualified person reviews every post before it is published. cmo.so keeps approvals on by default, and Content Policy Guard can hold a post that may break financial rules as a draft with a suggested rewrite.
Content Policy Guard gives AI suggestions, not legal or compliance advice. It does not make a post compliant on its own, and your business stays responsible for what it publishes.
How much does marketing automation cost for a lender?
There's a free plan with no card needed. Paid plans are per website and billed monthly: Air at £15 a month covers two posts a day, and Pro at £45 a month suits a lender posting to brokers and borrowers on several channels.
Founding members get lower prices for good on every plan until 1 January 2027. You can cancel any time.
Which channels should lenders start with?
Most lenders start with LinkedIn, because that's where brokers, introducers and business owners spend their working time, plus their own blog for borrower guides.
Google Business helps when people look you up by name, and Facebook (in beta) can suit consumer lenders. Each channel has its own posting times and queue.
Can posts avoid promising approval, rates or speed?
Posts can follow that rule every time. Add it to Content Policy Guard as a house rule, and a post that may break it is held as a draft with a suggested rewrite.
Your team also reads and approves every post, and Maggie learns from those edits.
Can cmo.so write for brokers as well as borrowers?
It can write for both, in different styles. Maggie writes broker-facing posts on criteria, products and case types for LinkedIn, and plainer guides for borrowers on your blog.
You choose the channels and the audience for each, and each channel has its own posting times and queue.
Will cmo.so publish our rates?
It only publishes what you approve. Maggie writes from your website and brand profile and doesn't invent figures, and many lenders choose to link to their product pages rather than quote rates in posts.
cmo.so never changes your products or rates, and you can edit any post before approving it.
Does it connect to our loan origination or CRM system?
It doesn't connect to loan, CRM or client record systems. Maggie works from your public website and your brand profile, so customer data stays where it is.
cmo.so never sells or rents data, and social channels connect through each platform's official sign-in, so cmo.so never sees your passwords.
Do we keep a record of what was published?
Every published post is reported back with its link, so you can see what went out, where and when.
Approvals are set per channel, so your compliance lead can keep sign-off on every channel.
Can different people approve different channels?
Yes. In Me → Team you can add people and choose what each can see or change, using presets such as editor or manager.
So marketing can prepare posts while compliance approves what goes out.
Keep brokers and borrowers informed, with every post approved
Enter your website. Your brand profile and first week of posts are ready in minutes, and nothing goes out until your team approves it.
- Free plan, no card needed
- You approve every post
- Cancel any time